Press Releases
FRA Holds Training Program for CAPMAS Staff Under Joint Cooperation Protocol – Sunday 25 October 2026
Dr. Islam Azzam – FRA Chairman:
- Training Serves as Key Pillar for Protocol Goals: Enhancing Report Quality and Indicator Accuracy Across Non-Banking Financial Activities
Financial Regulatory Authority (FRA), through its training arm, the Financial Services Institute (FSI), has launched a comprehensive training program for employees of the Central Agency for Public Mobilization and Statistics (CAPMAS). The five-day initiative focuses on financial data analysis, non-banking financial activity indicators, and advanced statistical extraction to support national economic decision-making. The program forms part of the operational roadmap under a strategic cooperation protocol signed between FRA and CAPMAS to unify statistical metrics and optimize their use in drafting reports and shaping economic policies.
FRA Chairman Dr. Islam Azzam stated that training is vital to realizing the protocol’s goals, particularly streamlining the exchange and availability of statistical metrics. This initiative aims to elevate data accuracy in official reporting, improve statistical workflows, curb duplicate information requests to businesses, reduce administrative overhead and deliver robust analytics for monitoring economic performance and future growth trends.
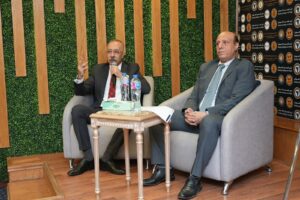
The program was inaugurated by Mr. Mohamed El-Sayyad and Dr. Tarek Seif FRA Vice Chairman as part of ongoing institutional cooperation between FRA and CAPMAS. The initiative aims to foster technical knowledge sharing and build institutional capacity for analyzing financial data and extracting statistical indicators that reflect developments across FRA-regulated sectors.
During the opening ceremony, Mr. Mohamed El-Sayyad welcomed CAPMAS trainees, emphasizing the crucial role of accurate data and statistics in analyzing non-banking financial activities—particularly capital markets and exchanges. He noted that robust metrics are essential for tracking market performance, measuring activity indicators and supporting objective decision-making. Mr. El-Sayyad also highlighted the establishment and evolving mandate of FRA, outlining its regulatory scope which balances market stability with the protection of participant rights.
For his part, Dr. Tarek Seif reviewed the key legislation and regulatory frameworks governing the Authority’s operations, along with international accounting standards and their importance in enhancing financial disclosure, transparency and data comparability. Dr. Seif also highlighted the pivotal role of Egypt’s insurance sector, stressing that reliable statistical data and metrics are vital for evaluating sector performance, monitoring activity growth and driving efficient supervision, strategic planning and policy formulation.
Spanning five days, the program covered the regulatory mandate of the Financial Regulatory Authority (FRA), the entities under its supervision and the role of non-banking financial activities in supporting the national economy. It introduced key non-banking financing activities, including financial leasing, factoring, consumer finance, mortgage finance, and SME and microfinance.
A full module focused on capital markets, covering brokerage firms, custodians, asset managers, the Egyptian Exchange (EGX), and clearing and settlement operations. The session provided hands-on training in key financial metrics—including liquidity, profitability, solvency, and operational efficiency—backed by practical case studies analyzing published brokerage data.
Another full day focused on the insurance sector, examining company structures, reinsurance, brokerage activities, and insurance products. Training centered on analyzing data related to premiums, claims, technical reserves, provisions, investments and underwriting surplus, complemented by practical application extracting relevant metrics from insurance company disclosures.
The curriculum also covered financial statement analysis for insurance and brokerage firms, familiarizing trainees with the components of balance sheets, income statements, cash flow statements, and supplementary notes. Participants analyzed revenue streams, commissions, financial assets, liabilities and client balances using real-world published financial statements.
The program concluded with a specialized module on financial and statistical analysis, covering horizontal and vertical analysis techniques, financial ratios (liquidity, profitability, activity, and capital structure), growth rates, sector averages, and performance benchmarks. It also addressed data quality verification, consistency checks, comparability, error correction and generation of statistical tables, sectoral indicators, periodic reports and databases.
The implementation of this program reflects the commitment of both FRA and CAPMAS to activate their cooperation protocol, foster database integration, and enhance staff technical capabilities. Ultimately, the initiative aims to generate reliable, up-to-date statistical indicators and elevate non-banking financial analysis while upholding the highest standards of accuracy, confidentiality and data protection in service of economic planning and decision-making.
FRA Issues Q3 2026 Investment Fund Report: Net Assets Exceed Half-Trillion EGP – Sunday 25 October 2026
- Investment fund certificates hit 52.5 Billion as retail investors hold 80% Share.
- Private equity funds led performance with an average yield of 15.24%, followed by index funds at 13.03%.
Financial Regulatory Authority (FRA), chaired by Dr. Islam Azzam, has issued Q3 2026 Investment Fund Report, tracking non-banking financial market developments through the end of September 2026.
The report highlights sustained expansion in total assets under management—crossing half trillion EGP—alongside a steady broadening of the investor base. Total fund certificates rose by more than 19% compared to the second quarter of the year, underscoring the growing role of investment funds as a key vehicle in the Egyptian capital market.
According to the report, the total number of registered funds across various asset classes expanded to 232 funds by the end of September 2026, up from 224 funds at the end of Q2.
The report details significant growth in key industry indicators and highlights expanding range of available investment options. The total number of funds rose to 232 by the end of September 2026, up from 224 funds at the end of the second quarter.
He highlighted that the market now offers an unprecedented variety of investment tools and products—ranging from equity and money market funds to precious metals, private equity, index and real estate funds. This wide array provides investors across all segments with innovative savings and investment channels tailored to their goals, while offering effective mechanisms to diversify risk and generate sustainable returns, ultimately supporting national economic stability and boosting financial and investment inclusion across Egypt.
According to the report, net assets under management in mutual funds reached EGP 504.71 billion by the end of September 2026, up from EGP 470.97 billion at the end of June. This marks an increase of EGP 33.74 billion, representing a growth rate of approximately 7.16% during the third quarter.
Local currency-denominated assets totaled EGP 470.10 billion, while foreign currency holdings reached the equivalent of EGP 34.60 billion, reflecting ongoing portfolio diversification across currency classes.
Total assets managed by funds rose to approximately EGP 512.84 billion by the end of September, compared to EGP 478.10 billion at the end of Q2, recording a quarterly growth rate of 7.27%.
In addition, the volume of issued fund certificates continued its upward trajectory, reaching 52.50 billion certificates by late September, up from 44.04 billion at the end of June—a surge of 19.21% over the three-month period.
Retail participants secured the biggest share of market ownership with 41.90 billion certificates, representing 79.8% of total holdings. Corporate and legal entities accounted for 10.16 billion certificates (19.4%), while founding institutions retained 441.7 million earmarked certificates, or 0.8% of total issuance.
Regarding investment performance during the third quarter of 2026, private equity funds outperformed all other categories with a top-tier average return of 15.24%. Index funds followed closely with a 13.03% average return, while single-sector funds delivered 12.23%. Precious metals funds and Islamic equity funds also posted solid gains, yielding average returns of 8.23% and 8.00% respectively. Rounding out the quarterly results, transferable securities funds returned 6.76%, thematic funds focusing on IT, fintech, and innovation ecosystems averaged 5.68%, and broader equity funds closed the quarter at 5.55%.
These positive indicators reflect expanding investor confidence and a steady rollout of regulated financial products across Egypt. Through its ongoing efforts to deepen non-banking financial markets, FRA continues to broaden investment vehicles tailored to diverse investor profiles, further bolstering the overall attraction and competitiveness of the Egyptian capital market.
FRA Issues Model Short Selling Contracts for Brokerage Firms and Securities Borrowers – Wednesday 21 October 2026
Dr. Islam Azzam, FRA Chairman:
- Standardizing contracts to boost market transparency and streamline client-broker relations.
- Setting clear rules for party obligations, collateral management and position closing.
- Engaging market stakeholders during live central lending system trials.
In a pivotal step toward the official launch of short selling in Egyptian capital markets, Dr. Islam Azzam, FRA Chairman has issued a decision approving model short selling contract for brokerage firms and securities borrowers. Enacted under the new regulatory framework established by FRA Board Decree No. 155 of 2026, the decision establishes a clear contractual framework governing the relationship between the securities borrower—seeking to borrow securities available on the central lending platform at Misr for Central Clearing, Depository and Registry (MCDR)—and the licensed brokerage firm executing transactions on the borrower’s behalf.).
Short selling mechanism operates on the presence of a lending client who wishes to lend owned shares and securities borrower who seeks to borrow shares to execute a short sale with the intent to repurchase and return them to the lender at a later date if the stock price is expected to decline. Profit is thereby realized from the price differential between the sale and purchase prices, based on the investor’s market expectations and price projections, pursuant to a binding agreement executed with a licensed brokerage firm.
This model contract was finalized following extensive consultations with market stakeholders to leverage industry expertise and address practical operational requirements. This collaborative approach reflects FRA’s commitment to constructive community dialogue, ensuring the development of enforceable rules that balance operational efficiency, risk management, and investor protection.
The template comprehensively defines the procedural roles, rights and obligations of both brokerage firms and securities borrowers. It regulates key operational aspects including fees, commissions, and the distribution of yields generated from invested cash collateral. These provisions enhance operational efficiency, promote market transparency, and ensure investors fully understand the mechanism, its associated risks, margin maintenance protocols, and position closure triggers under regulatory or contractual rules.
To mitigate operational and market risks, the contract establishes several mandatory safeguards. Borrowers must post initial margin collateral—at or above the minimum thresholds mandated by FRA regulations—as specified in the contract annex prior to execution, while brokerage firms are legally required to deposit cash collateral into dedicated, segregated accounts restricted to short-selling transactions.
Furthermore, to minimize counterparty risk and safeguard market integrity, brokerages must continuously mark borrowed securities to market using real-time intraday closing prices and monitor the collateral-to-borrowed-securities ratio against regulatory and contractual minimums.
The contract sets clear protocols for defaults or delays in returning borrowed shares, requiring the brokerage to execute mandatory buy-ins subject to standard settlement cycles. It also outlines mandatory position closure events, such as a security’s removal from the eligible trading list or regulatory triggers arising from corporate actions like M&As, tender offers, spin-offs, or liquidations.
In addition, brokerage firms are obligated to provide clients with a comprehensive guide detailing short selling concepts, operational mechanics, risks and benefits, updating this guide after any regulatory revisions and distributing it to clients at least annually.
Regarding financial terms and yield management, cash collateral must be invested exclusively in FRA-approved instruments throughout the lending period. Brokers must inform clients of investment channels and actual yields, crediting returns directly to the client’s account upon receipt or according to agreed terms.
Regarding borrowing costs, the model contract mandates that brokerage firms clarify all expenses, commissions and other cash charges debited from the client, clearly stating the calculation basis for each. Future modifications to fees and commissions are strictly prohibited without the client’s explicit written consent.
Furthermore, the model guarantees the client’s right to issue buy and sell orders for borrowed securities, as well as to fully or partially close their open positions during the borrowing term in accordance with contractual provisions.
Dr. Islam Azzam highlighted that the model contract is a key milestone toward fully enabling short selling across Egyptian capital markets. The Authority is currently finalizing technical guidelines and practical manuals for all market participants in tandem with fine-tuning the MCDR Central Securities Lending (CSL) system through live trials. This ensures real-time operational integration between MCDR and brokerage firms, complete end-to-end transaction logging, and full market visibility. Under this setup, borrowers can view all available lending offers to select options aligned with their investment goals, while lenders can monitor market-wide lending bids.
FRA Chairman added that the standard contract unifies market practices, establishes clear operational boundaries for collateral administration, enforces position monitoring, and outlines strict remedies for margin calls or delayed share returns to protect all market participants.
To ensure regulatory and legal compliance, borrowers must explicitly certify ultimate beneficial ownership of the account, declare legitimate sources of funds, and submit required Customer Due Diligence (CDD) data pursuant to Anti-Money Laundering (AML) Law No. 80 of 2002 and related non-banking financial regulatory decrees.
Furthermore, licensed brokerages are bound by strict confidentiality mandates prohibiting the disclosure of client data or transaction records to third parties without prior written consent, except when responding to regulatory reporting mandates from FRA or lawful judicial orders.
It is worth noting that in a short-selling transaction, the securities borrower profits if their expectations of a drop in the borrowed security’s price are realized. In this scenario, the borrower repurchases the shares at a lower market price to lock in a profit margin and returns them to the lender, with borrowing costs deducted from the realized profit. Conversely, if the security’s price rises and the borrower wishes to limit their losses, they must repurchase the shares at the higher market price, incurring a loss in addition to paying borrowing costs.
In both cases, the securities lender earns a yield for lending their securities—typically approximating the risk-free rate plus an additional lending premium—while continuing to retain all underlying economic benefits associated with stock ownership.